

Support at Home contributions explained
See what you'll pay under Support at Home: 0% for clinical care, means-tested rates for other services, a lifetime cap, and no-worse-off protection.
Author: Sensible Care
Support at Home contributions are what you pay for non-clinical supports out-of-pocket. Clinical care is 0% when it's on your plan. Your share is a percentage of the service price, set by a means test and limited by a lifetime cap. If you moved from a Home Care Package, no-worse-off protections apply.
Under Support at Home, you only contribute toward some day-to-day, non-clinical supports. For example, you'd contribute toward cleaning or meal prep, but not clinical nursing care. The government covers the rest.
Your out-of-pocket costs are called Support at Home contributions. Your contribution is based on your income and assets, with a lifetime cap on total payments.
Clinically required care (nursing or physiotherapy on your approved plan) is fully funded. You don't have to pay anything for those services.
If you need help at any point, Sensible Care can walk you through your assessment, statements, and service options.
What are Support at Home participant contributions?
Support at Home contributions are out-of-pocket expenses for certain non-clinical home supports. The Australian Government pays the rest of the bill as a subsidy.
When Home Care Packages transitioned to Support at Home, clinical care became fully covered. If a clinical service (like nursing or physiotherapy) is on your approved care plan, your contribution is 0%.
Contributions apply to non-clinical supports, which may include:
- Personal care
- Domestic help
- Meal preparation and shopping
- Some consumables
- Assistive technology
- Minor home modifications
Personal care will move out of this group on 1 October 2026. It will be classified as a Clinical support and fully funded by the Government.
In other words, you won't pay a contribution for approved personal care. You don't need to be reassessed, and contributions for other services are unchanged.
Your contribution is a percentage of the service price. You only pay for what you receive, and there are no standing charges or standby fees. Late cancellations and missed appointments are the one exception.
How to calculate your contribution?
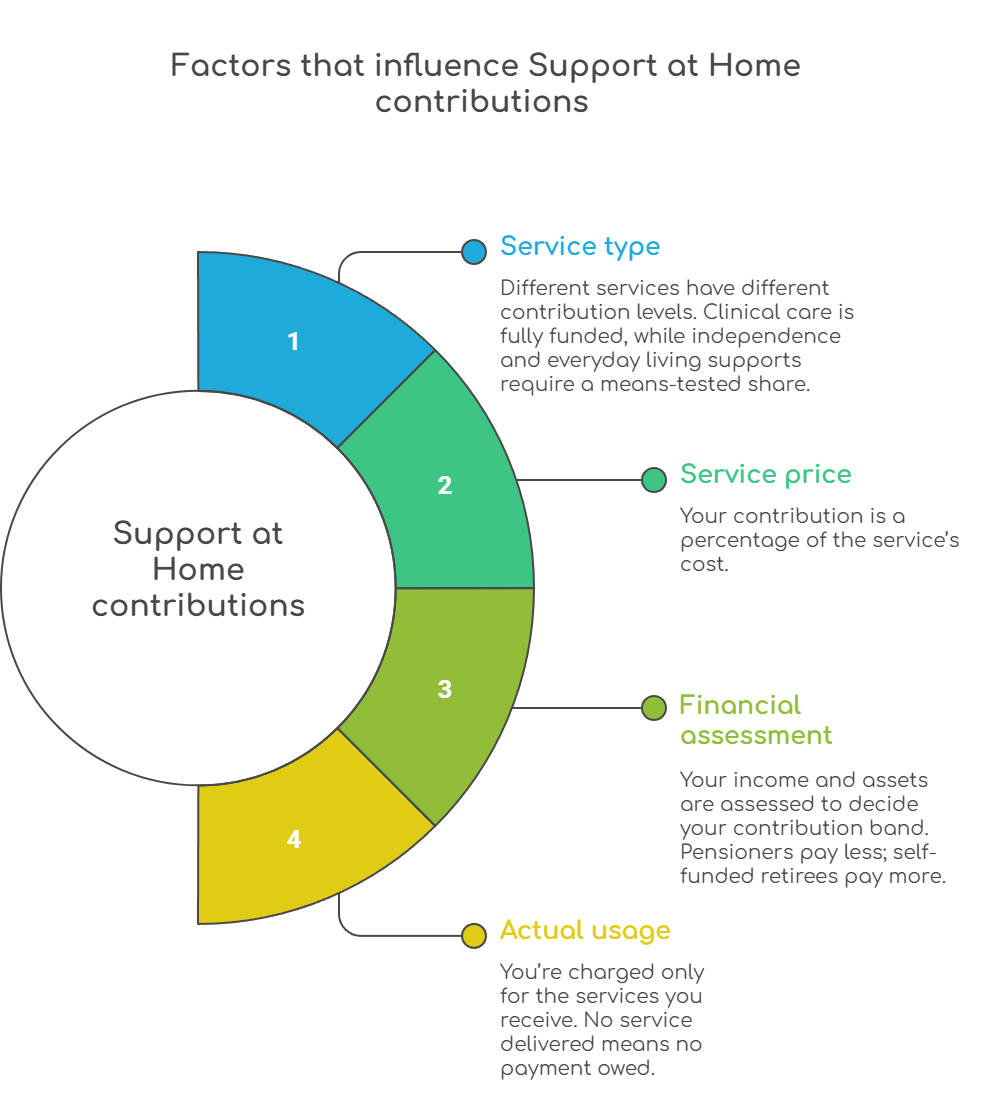
Your out-of-pocket amount isn't a flat fee. It's worked out each time you receive a service. Four factors affect what you pay:
- Service type
- Service price
- Your financial assessment
- How much you actually use
Service type
Support at Home distinguishes three service types. Each type has different funding rules and contribution levels.
- Clinical (e.g., nursing, physio): 0% contribution when clinically required and on your plan.
- Independence (e.g., personal care, assistive technology, minor home modifications): moderate contribution.
- Everyday living (e.g., domestic help, meal preparation, shopping): highest contribution.
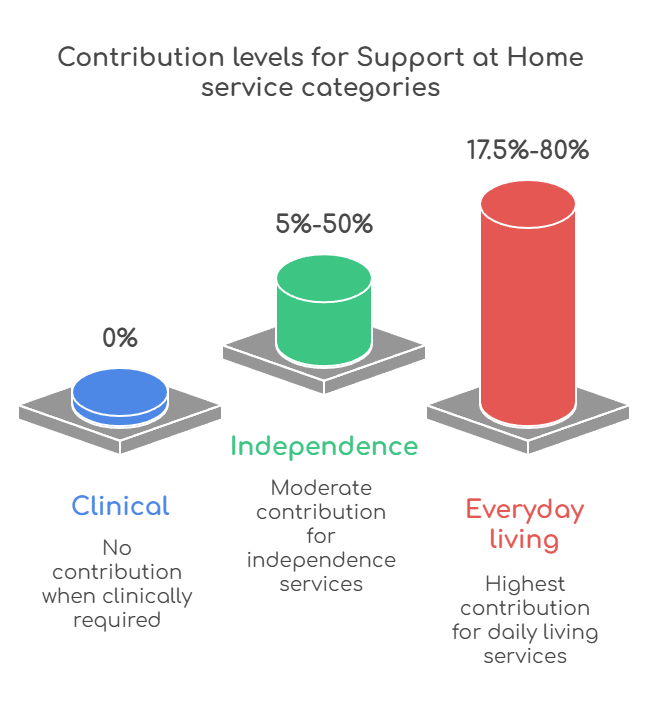
The same person could pay 0% for a nurse visit and 17.5% to 80% for domestic help, because they're different service types.
Clinical services (0% contribution)
Clinical services are medical or therapeutic supports provided by qualified health professionals. They can include nursing, wound care, or physiotherapy. From 1 October 2026, personal care will join this category too.
When the service is clinically required and listed in your approved care plan, you pay nothing. The Australian Government covers the full cost of delivery.
Independence services (moderate contribution)
This category covers supports designed to help you maintain or improve your independence at home and stay safe. Examples include:
- Personal care (showering and dressing) — moving to Clinical on 1 October 2026
- Installing assistive technology
- Minor home modifications
Contributions for these services are means-tested. They range from 5% for full pensioners to 50% for self-funded retirees.
From 1 October 2026, personal care leaves this category and becomes fully funded. So, that range applies only to the remaining Independence services.
Everyday living services (higher contribution)
These are day-to-day tasks that keep your home running smoothly, like:
- Cleaning
- Laundry
- Meal preparation
- Gardening
Because they're not clinical or directly tied to medical need, they have the highest contribution rates. Depending on your financial situation, you may contribute between 17.5% and 80% of the service cost.
Service price
Each service under Support at Home has a price.
Since Support at Home began on 1 November 2025, providers have set their own prices within government guidelines. This allowed for flexibility while the system transitioned from Home Care Packages.
Official price caps were due to start on 1 July 2026, but the Government deferred them in May 2026 and has not set a new date. Providers continue to set their own prices in the meantime. Those prices must still be reasonable and reflect the real cost of delivering care.
Your contribution is a percentage of each service's price. Even if your contribution percentage stays the same, your dollar amount will change depending on the price of each service.
For example, if a cleaning service costs $100 and your contribution rate is 17.5%, you'll pay $17.50. If the same service costs $120, your contribution increases to $21, because your share is based on the higher price.
With older programs, providers could add separate charges. Support at Home requires transparent pricing. This means:
- Service prices must include the full delivery cost (worker time, overheads, travel).
- Care management is separate: 10% of your quarterly budget goes into a pooled account, shown as its own line item.
- No package management fees or hidden add-ons beyond the service price and care management allocation.
Your financial assessment
Your Support at Home contributions may also depend on your financial assessment. This process ensures contributions are fair and based on your capacity to pay, rather than a one-size-fits-all fee.
The review considers your personal income, or your joint income if you're a couple, and your financial resources. The assessment excludes the home you live in. However, it factors in savings, investments, other assets such as vehicles, and other income sources.
Once your assessment is complete, you're placed into a contribution band:
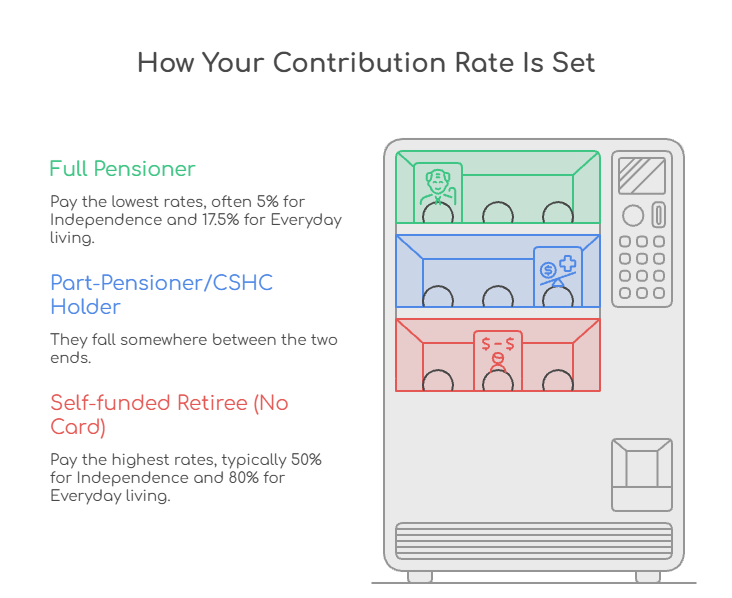
- Full pensioners
- Part-pensioners and Commonwealth Seniors Health Card (CSHC) holders
- Self-funded retirees
Full pensioners pay the lowest contribution rates. It's often just 5% for Independence services and 17.5% for Everyday living supports.
The second group includes Part-pensioners and Commonwealth Seniors Health Card (CSHC) holders. It also includes self-funded retirees who hold a CSHC. They sit on a sliding scale between those two ends.
Your exact rate depends on your assessed means and rises gradually rather than jumping between fixed steps.
Self-funded retirees without concession cards contribute at the highest rates. It's typically 50% for Independence and 80% for Everyday living services.
Your financial assessment ensures the system remains fair and transparent. Those with lower incomes receive more government support. Those with greater means contribute more.
If you transitioned from a Home Care Package, grandfathering arrangements apply to you. This means you keep your assessed contribution instead of moving to standard Support at Home rates. If you paid no income-tested care fee under your HCP, you won't pay contributions under Support at Home either.
How much you actually use
Support at Home operates on a pay-as-you-go basis, which means you're only billed for services you actually receive.
There are no standing charges or "retainer" fees. You only pay when a service is delivered. Late cancellations/no-shows may still attract a charge.
Each time you receive a service, whether it's an hour of personal care or a domestic help visit, it's logged by your provider. The cost of that service is then split between you and the government according to your contribution rate.
Cancellation notice periods are set out in your service agreement with your provider. If you cancel with enough notice, there's no charge. If you cancel late or no-show, you may still owe your usual contribution.
Your monthly/quarterly statements will show:
- The service type (Clinical, Independence, or Everyday living)
- The full-service price
- Your contribution (both the percentage and dollar amount)
- The government subsidy that covers the rest
This transparency helps you see exactly what you're paying for and ensures your total spending stays within your budget.
Contributions for former Home Care Package recipients
The "no-worse-off" rule applies if you:
- Transitioned from a Home Care Package (HCP)
- Were approved for a package, or on the National Priority System, on or before 12 September 2024
This protection ensured that moving to the new program wouldn't increase your costs. Your out-of-pocket contributions did not increase because of the program change. You pay the same or less than you did under HCP for comparable non-clinical support.
It also means you have a discounted contribution schedule (a lower lifetime cap of $86,185.23, as at 20 March 2026). This uses lower percentages than the standard Support at Home rates for new entrants.
If your needs change later and you're reassessed, the no-worse-off settings still prevent you from paying more because of the reform.
How to confirm you're covered:
- Check your My Aged Care letters or portal for your transition status.
- Ask your provider to confirm which contribution schedule they're applying to you.
- If something looks off on your invoice, raise it with your provider first; they can check with My Aged Care/Services Australia.
How the lifetime payment cap works
Support at Home has a built-in safeguard called the lifetime cap. It limits how much you can pay for non-clinical services over your lifetime.
Once your total contributions reach the cap, you stop paying for these types of support. The Australian Government covers the full cost from that point on.
The lifetime cap is $137,917.01 (as at 20 March 2026). This amount is indexed twice a year, on 20 March and 20 September, to keep up with inflation and cost changes. Make sure to check the current figure with your provider or Services Australia before relying on it.
The lifetime cap only applies to non-clinical services. Clinical care (like nursing or physiotherapy) is fully funded and never counted toward the cap.
Services Australia tracks your payments automatically, so you don't need to do anything to monitor your progress.
If you were already receiving a Home Care Package, you may have a lower lifetime cap under the no-worse-off protection rules.
This system ensures that your total out-of-pocket costs for non-clinical support stay:
- Fair
- Predictable
- Within a clear limit
How contributions link to residential aged care
If you transition from Support at Home to residential aged care in the future, your contributions follow you.
The lifetime cap applies across both settings - home care and residential care.
For residential aged care, there are two ways the cap can be reached:
- Dollar limit: When your total non-clinical care contributions reach $137,917.01 (as at 20 March 2026, indexed twice yearly), or
- Time limit: After you've been paying contributions for four years, whichever comes first.
Support at Home contributions count toward the dollar limit, but not toward the four-year time limit. The four-year clock counts only the time you spend paying the non-clinical care contribution in residential aged care. It doesn't start running while you're receiving care at home.
Let's say you've already paid $50,000 in Support at Home contributions. You would then only need to pay $87,917.01 more (or less, depending on indexing) in residential care before reaching the dollar cap.
This combined approach ensures you're protected from excessive lifetime costs. The same applies when you receive care at home, in residential aged care, or both.
FAQ
Do I have to pay for clinical services like nursing or physiotherapy?
No. If a clinical service is approved as part of your care plan, it's fully funded by the government. You won't pay a participant contribution for it.
Which services do I contribute to?
You'll usually contribute to non-clinical supports. For example, domestic help, meal preparation, transport, and assistive technology. These fall under Independence or Everyday living services.
Personal care sits under Independence until 1 October 2026, when it becomes fully funded and moves to Clinical.
Do I pay for cancelled or unused services?
Mostly, no. You're charged only for services you actually receive, and there are no standing or retainer fees.
The exception is late cancellations and missed appointments. If you cancel late or aren't home for a visit, you may also be charged your usual contribution.
When do government price caps start?
There's no start date at the moment. Caps were scheduled for 1 July 2026, but the Government deferred them in May 2026 and hasn't announced a new date. Until they start, providers set their own prices, which must still be reasonable and reflect the cost of delivering care.
Making Support at Home simple, fair, and affordable with Sensible Care
The Support at Home program makes it easier to see what you pay, what's covered, and how much protection you have.
Clear rates, lifetime caps, and safeguards for those who transitioned from Home Care Packages keep home supports affordable. The system is designed to stay transparent throughout.
At Sensible Care, we know these changes can be confusing. But you don't have to figure them out alone. Our friendly team can help you:
- Understand your Services Australia assessment and contribution rate.
- Review your care plan and statements for accuracy.
- Arrange the right mix of services to suit your needs and budget.
Contact Sensible Care today or book a free consultation to discuss your Support at Home plan. We'll ensure you understand your options and get the care you deserve without paying more than you should.

Take the Next Step in Care
Download our Info Kit or speak to one of our friendly team members today.


Explore More Helpful Reads
More stories, guides, and updates to support you and your family.


Need Help Getting Started?
Reach out on your terms, pick a time that suits you and let’s talk about how we can help.


